Table of Contents
- How Fast Do Homes Sell in the Tri-County Area?
- Step 1: Price It Right From Day One
- Step 2: Best Practices for Home Staging That Drive Offers
- Step 3: Marketing That Puts Your Home in Front of Buyers
- Selling a Home With a Mortgage: What You Need to Know
- Cash Offers vs. Traditional Sales: Which Gets You to Closing Faster?
- Common Mistakes That Slow Down a Charleston Home Sale
- Conclusion: Your Plan to Sell Charleston Home Fast
- Frequently Asked Questions
Last Updated: September 6, 2026
Selling a home in Charleston doesn’t have to mean waiting months for the right offer. How to sell charleston home fast comes down to a handful of strategic decisions made before you ever put the sign in the yard. At The Mills Team, we’ve guided over 2,000 property sales across the Tri-County area, and the difference between a quick closing and a longer listing almost always traces back to pricing, presentation, and preparation.
Charleston’s real estate market has consistently favored sellers in recent years, with buyer demand remaining strong across popular neighborhoods. But a hot market alone won’t sell your home if it’s priced wrong or presented poorly.
How Fast Do Homes Sell in the Tri-County Area?
The answer isn’t a single number, it’s a curve that shifts with the calendar and the neighborhood. While a well-priced home in a desirable pocket can go under contract in under two weeks, the median days-on-market across the tri-county area tells a more nuanced story. Your timeline is dictated by your specific micro-market and the season you choose to list.
Charleston’s market is uniquely tied to its tourism and relocation cycles. The most active buyer periods typically align with the spring and early summer months (roughly March through June), when corporate relocations peak and out-of-state buyers are scouting during visits. A second, smaller surge often occurs in the early fall (September through October) as buyers aim to close before the holidays. Listing in the deep winter weeks between Thanksgiving and New Year’s can be a strategic play, there’s less inventory, and the buyers who are looking are often more serious and less distracted by competing open houses.
Here’s how that seasonality plays out across the region’s distinct sub-markets:
- Downtown Charleston: The historic district and the peninsula operate on their own cycle. Inventory is perpetually tight, but buyer pools are smaller and more specific. A correctly priced single-family home or condo can still attract an offer within 7-14 days, but the buyer is often a cash purchaser or someone with a jumbo loan who is not contingent on selling their own property first. The luxury segment ($1.5M+) moves slower, often 45-60 days, as it relies on a thinner pool of qualified buyers.
- Mount Pleasant: This is the heart of the family-oriented, relocation-driven market. Homes in the $600k-$900k range that are turn-key and in top school districts routinely see multiple offers within the first week. The market here is less forgiving of overpricing; buyers are well-informed and compare against a deep pool of recent sales.
- West Ashley & James Island: These areas offer a mix of established neighborhoods and newer developments. The buyer pool is more price-sensitive. A home priced correctly in the $400k-$600k band can still see an offer in 2-3 weeks, but you’re more likely to encounter a buyer who needs to sell their own home first, which can extend your closing timeline.
- Summerville & the ‘Burbs: The market here is driven by value and new construction. You’re not just competing against resale homes; you’re competing against builders offering incentives. A quick sale here demands aggressive pricing and a clean, move-in-ready presentation to outshine the allure of a brand-new build.
The most reliable way to gauge your timeline isn’t a national statistic, it’s a comparative market analysis (CMA) prepared by a local agent who is actively tracking the absorption rate in your specific neighborhood. The absorption rate (how many months it would take to sell all current inventory at the current pace) is the single most telling metric. If your neighborhood has a 1.5-month supply, you’re in a seller’s market and can price more firmly. If it’s a 5-month supply, you need to be the best-priced, best-presented home in your immediate competition to win.
Sellers often wait until spring to list, assuming that’s always the best time. But in Charleston, a well-executed winter listing in a high-demand pocket like Mount Pleasant can face 50% less competition, meaning your home gets a disproportionate share of serious buyer attention.
Before you set a list date, ask your agent for the absorption rate for your specific neighborhood and price band over the last 90 days. This number is a far better predictor of your timeline than any general market forecast.
Step 1: Price It Right From Day One
Pricing strategy is the single biggest factor in how quickly your home sells. Homes priced at or slightly below fair market value from the first day generate more showings, more competition, and often final offers above asking. The opposite happens when you start too high and chase the market down with price reductions.
A common mistake is anchoring to what a neighbor “said they got” or what you need to clear after paying off your mortgage. Buyers don’t care what you owe, they care what comparable homes are actually selling for right now.
Your pricing should be based on a fresh comparative market analysis, not outdated estimates or emotional attachment. An agent-prepared home valuation that reflects current closed sales, pending sales, and active competition gives you the clearest picture of where to set your list price.
Overpricing by even 5 percent can cost you weeks of market time, and homes that sit for 30+ days often sell for less than they would have fetched with an aggressive initial price. The first two weeks of showings generate the most buyer interest.
Step 2: Best Practices for Home Staging That Drive Offers
Home staging is arranging your furniture and decor so buyers can picture themselves living in the space. The goal is neutral, decluttered, and welcoming, buyers need to see the home’s bones, not your personal style.
Start with decluttering every room, removing personal photos, and clearing countertops. Then tackle curb appeal, since buyers often decide within seconds of pulling up whether they want to see more. Fresh mulch, trimmed shrubs, and a clean entryway make a strong first impression.
For most homes, a deep clean and strategic furniture rearrangement delivers the best return. You don’t need to rent furniture or repaint every wall. Focus on the rooms buyers weigh most heavily: the kitchen, the primary suite, and the living area.
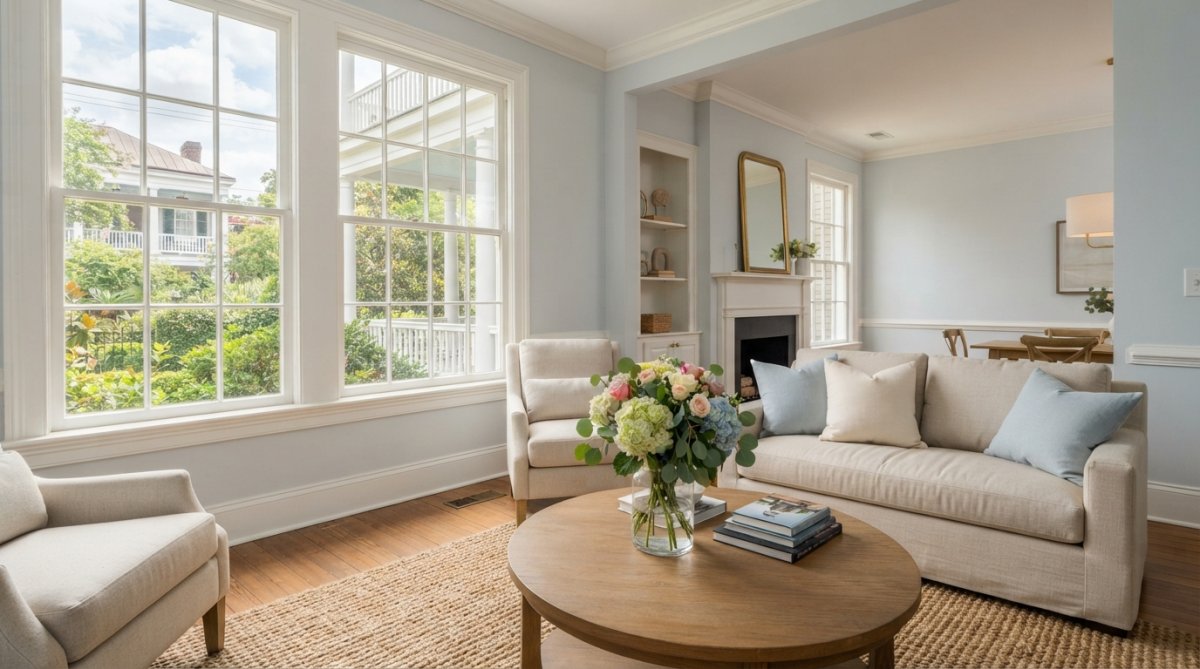
Home staging best practices also include addressing minor repairs buyers will notice. Fix leaky faucets, replace burnt-out bulbs, and touch up scuffed paint. These small investments signal that the home has been maintained, which reduces buyer anxiety about hidden problems.
Step 3: Marketing That Puts Your Home in Front of Buyers
Professional photography is non-negotiable. Listings with high-quality photos receive significantly more views than those with amateur shots, and most buyers begin their search online. Your listing photos are your first showing.
Beyond the MLS listing, a multi-tier marketing approach ensures your home reaches the widest pool of qualified buyers. This includes syndication to major real estate portals, targeted social media exposure, and direct outreach to agents whose buyers are actively searching in your neighborhood.
A listing agent with local reach can also tap into their buyer network before the home ever hits the public market. Many Charleston agents have clients waiting for specific neighborhoods or price ranges, and a private showing can generate an offer within days.
Selling a Home With a Mortgage: What You Need to Know
Selling a home with a mortgage is completely routine. The proceeds from your sale pay off your remaining loan balance at closing, and you keep whatever equity remains after closing costs and agent commissions. You do not need to pay off your mortgage before listing.
What matters is understanding your numbers before you price the home. Request a payoff statement from your lender to see the exact amount needed to clear your loan, including any prepayment penalties or accrued interest. Then subtract estimated closing costs to calculate your net proceeds.
If your home is worth less than what you owe, a short sale may be an option, though it requires lender approval and typically takes longer. Most Charleston homeowners selling today have built substantial equity, but it’s worth confirming your position early so there are no surprises at closing.
Cash Offers vs. Traditional Sales: Which Gets You to Closing Faster?
The surface-level answer is simple: cash closes faster. But the more important question for your net proceeds is who is making that cash offer and what the true cost of that speed is.
The Speed Advantage is Real, But Nuanced
A true cash offer from a buyer who has the funds liquid can close in 7-14 days. There is no appraisal, no underwriting, and no financing contingency. This is the fastest possible path to closing. However, most cash offers in the Charleston market come from real estate investors, and their offers are typically priced to reflect the risk they are taking on and the convenience they are providing. Expect an investor offer to be 10-20% below what a retail buyer might pay, depending on the condition of your home.
The Tax Angle Most Sellers Miss
The decision between a cash investor sale and a traditional sale has significant tax implications that are rarely discussed in generic guides. Under current federal tax law, you may exclude up to $250,000 of capital gains ($500,000 for married couples filing jointly) if you have owned and lived in the home for two of the last five years. This exclusion applies regardless of whether you sell to an investor or a traditional buyer.
However, the structure of the deal matters. If you sell to an investor who is buying your home as a rental property, the transaction is a straightforward asset sale. But if you are selling a property that you have not lived in recently (e.g., an inherited home or a rental), you will not qualify for the exclusion and will be subject to capital gains tax on the profit. In that scenario, the speed of a cash sale might be worth the tax hit, but you should calculate the net difference before signing.
If your home has significant deferred maintenance, a cash sale to an investor is treated as a sale ‘as-is,’ and you do not get to deduct the cost of repairs you didn’t make. In a traditional sale, you might spend $15,000 on repairs that can yield a $30,000+ increase in sale price. The investor’s discount is effectively a ‘phantom’ repair cost you absorb without the ability to itemize it.
The South Carolina Disclosure Factor
This is where speed can become a liability. South Carolina law requires sellers to complete a Property Condition Disclosure Statement about the home’s major systems and known defects. When you sell to a professional investor buying ‘as-is’ with no contingencies, they often waive their right to the disclosure form, but this does not fully absolve you of liability.
If you fail to disclose a known material defect, such as a leaking roof or foundation issue, and the investor later discovers it, you could still face a legal claim for fraud or misrepresentation. The waiver does not override state law regarding fraudulent concealment.
A Framework for Decision-Making
Instead of asking ‘cash or traditional?’, ask ‘what is my net proceeds difference and my risk tolerance?’
- Get the Investor Offer First: Have the investor put their offer in writing. This gives you a concrete baseline.
- Price the Traditional Route: Ask your agent for a realistic retail price after accounting for the cost of any necessary repairs or concessions you’d likely make to a traditional buyer.
- Calculate the Net: Subtract your estimated closing costs and any repair expenses from the traditional sale price. Subtract the investor’s offer from the cash price. The difference is the ‘cost of speed.’
- Assess Risk: The traditional sale carries the risk of a financing contingency falling through. The cash sale carries the risk of a lower price and the potential for legal exposure if you are not meticulous with your disclosures.
For many sellers, the 10-20% discount demanded by an investor is too high a price for saving 30 days. But for a seller facing a tight relocation deadline or complex estate situation, that discount is the price of certainty.
Regardless of who you sell to, never conceal a known material defect. In South Carolina, the duty to disclose known issues is a legal obligation, not a negotiating tactic. A fast sale is not worth the risk of a post-closing lawsuit.
Common Mistakes That Slow Down a Charleston Home Sale
The most common mistake is letting emotion drive pricing. Your home holds memories, but buyers evaluate it as a financial transaction. Overpricing to “see what happens” almost always backfires.
Another frequent error is skipping the home inspection before listing. A pre-listing inspection reveals issues you can address upfront or disclose honestly, rather than discovering them after a buyer’s inspection.
Property disclosure requirements in South Carolina obligate sellers to reveal known defects. Failing to disclose a material issue can lead to legal disputes after closing, so transparency from the start protects you and keeps the transaction on track.
Conclusion: Your Plan to Sell Charleston Home Fast
Selling quickly requires discipline: price it right, present it well, and market it aggressively from day one. The Mills Team combines 69-plus years of local experience with a proven 45-day home selling system and a 3% listing fee structure. Get started with The Mills Team and put your home on the path to achieving your real estate goals.
Frequently Asked Questions
What is the best time of year to sell a home in Charleston?
The spring and early summer months typically see the highest buyer demand and the shortest days on market in the Tri-County area. However, a well-priced and professionally marketed home can sell quickly at any time of year. The key is aligning your pricing strategy with current local market conditions rather than waiting for a specific season.
Can I sell my Charleston house fast if I still have a mortgage?
Yes, selling a home with a mortgage is a standard transaction. The sale proceeds pay off your remaining loan balance at closing, and you keep any remaining equity. Your listing agent will coordinate with your lender to obtain a payoff statement. The process is straightforward and does not slow down the sale timeline.
What is the 3-3-3 rule in real estate?
The 3-3-3 rule is a common guideline that suggests a home sale can take roughly three days to prepare, three weeks to market and show, and three months to close. While it is a useful expectation-setting framework, the actual timeline in Charleston depends on pricing, condition, and buyer demand in your specific neighborhood.
What devalues a house the most in a fast sale?
Overpricing is the single biggest factor that devalues a home and extends its time on the market. Poor curb appeal, deferred maintenance, and strong odors also deter buyers. Instead of making expensive upgrades, focus on deep cleaning, decluttering, and making minor repairs that improve the home’s perceived value and attract more offers.